

By Amias Gerety
The most important strategic question in insurance distribution is whether to sell through agents or directly to the consumer. The answer, borne out over decades in auto insurance and increasingly in homeowners, is that direct-to-consumer (DTC) is the fundamentally superior model. The evidence is not ambiguous.
GEICO and Progressive: The DTC playbook
GEICO and Progressive are the two largest DTC auto insurers in America. Together, they hold roughly 28 percent of the U.S. personal auto insurance market, a position built almost entirely by eliminating agents and selling direct. In 1995, before GEICO was fully acquired by Berkshire Hathaway, its market share was less than 3 percent.
Today, it is among the top three U.S. auto insurers. Progressive has grown from a regional player to the second-largest U.S. auto insurer, overtaking GEICO in direct premiums written in 2022.
This dominance is not a coincidence. It is the direct result of the economics: traditional insurance agents take 15–20 percent of premiums in ongoing commissions, which is pure cost to the insurer (and ultimately the consumer) with no actuarial value added. By going direct, GEICO and Progressive captured that margin, priced more competitively, reinvested in technology and compounded their advantage over decades.
The shift to direct is also a consumer preference story. Nearly 47 percent of all insurance policy buyers now purchase through digital channels, up from 32 percent just five years ago. For younger homebuyers — the most attractive long-term cohort — that preference is even more pronounced. Consumers increasingly see no reason to pay an agent when they can get faster quotes, better pricing and direct service online.
Why DTC is structurally better for homeowners insurance
The DTC model is attractive in any insurance line, but it is especially powerful in homeowners insurance for several reinforcing reasons:
Margin capture: Cutting out external agents enables capturing the very lucrative (>30 percent EBITDA margins) distribution profit pool. Agents in homeowners insurance are paid on recurring commissions — every year, for the life of the policy.
Customer ownership: In an agent-distributed model, the agent owns the customer relationship. When they move, the customer moves with them. In DTC, the insurer owns the relationship and the lifetime value that comes with it.
Technology speed: Removing external parties from the value chain enables faster product and tech innovation — there’s a reason why the most innovative companies like Tesla and Apple want to control their own distribution rather than selling through traditional retailers. Some agents are great, others less so – going direct to consumer allows companies to own their own experiences.
Cross-sell platform: Homeowners insurance is an extraordinary cross-sell platform. People who own homes have an attractive financial profile, creating a natural foundation for auto, umbrella, flood and other products.
Risk-targeting: As our founders pioneered at Capital One, marketing only to the customers you actually want as customers increases efficiency and risk at the same time.
Three venture-backed bets on the same thesis
When QED invested in Kin in 2020, the thesis was clear: DTC was a fundamentally better approach to homeowners insurance, and no one had yet done it well at scale. But we were not alone in seeing this.
At the time, there were two other well-funded venture-backed companies pursuing a very similar vision: Hippo and Lemonade. Both launched around the same time as Kin, both raised hundreds of millions of dollars and both explicitly positioned themselves as tech-enabled, direct-to-consumer alternatives to the traditional agent model.
We saw Kin as the natural extension of the things we have loved in fintech since the founding of Capital One: a huge, underserved market where technology and data can make a meaningful difference in outcomes.
Six years later, the results are in. Kin is clearly the winner in direct-to-consumer homeowners insurance — fast growing, with excellent unit economics, while Hippo and Lemonade have failed to gain meaningful traction in the core homeowners market. Here is how each competitor played out.
Hippo: Abandoned the thesis
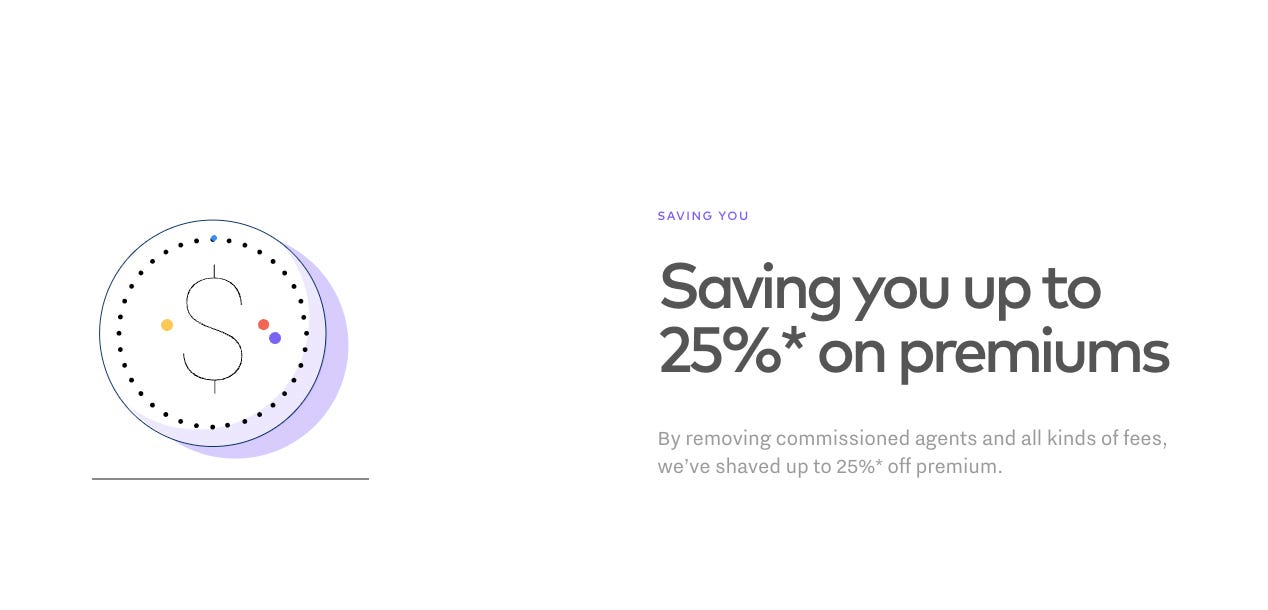
Hippo launched in 2017, the same year as Kin. In December 2017, the first page of myhippo.com emphasized that “by removing commissioned agents and all kinds of fees, we’ve shaved up to 25%* off premium.” But barely a year later, they had already moved to add an agent led model, and were aggressively marketing to agents.
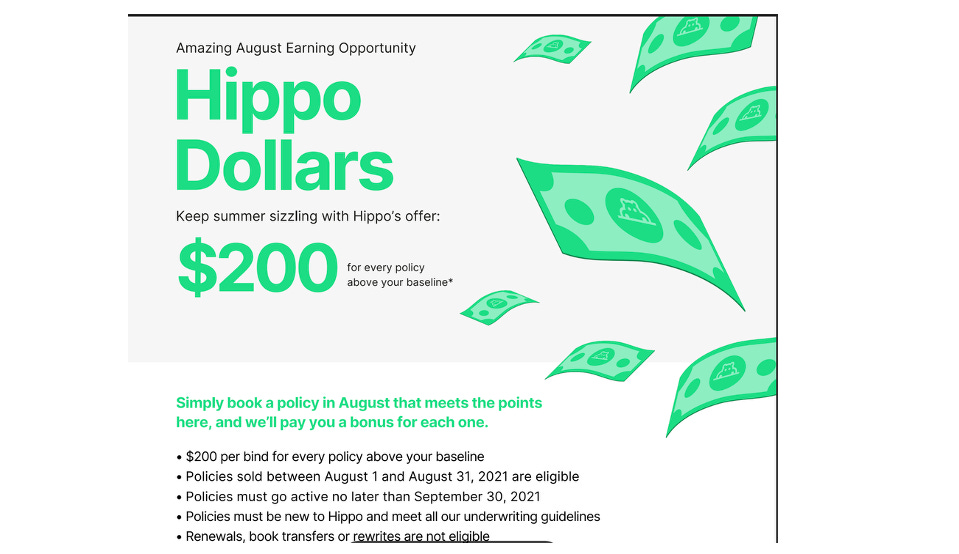
$200 per policy was no small prize. It likely more than doubled the 15 percent commission on an average homeowners policy. Naturally, agent distribution rapidly became the majority of Hippo’s premiums.

Direct to consumer is a fundamentally harder game, but it is also a bigger prize. Kin has always recognized that having a direct consumer relationship not only provides access to a bigger profit pool, it also provides better customer experience and better risk controls.
Eventually, Hippo not only pivoted away from direct to consumer, but away from homeowners insurance entirely, focusing on scaling the fronting business (similar to Rent a Charter in banking) called Spinnaker that it acquired in 2020, subsequently rebranded as “Insurance as a Service” or IaaS.
By 2023, Hippo entirely turned off its home insurance program after its loss ratio reached 178 percent. By 2024, the entirety of Hippo’s new home insurance volume was coming from distribution partnerships with their investor Lennar and other homebuilders. By Q2 2025, the focus at Hippo was clearly the legacy Spinnaker fronting business, which Hippo used to call Insurance as a Service and had been rebranded again as “Hybrid fronting.”
Also in Also in 2025, Hippo sold the homebuilder distribution to Baldwin, while acting as the fronting carrier, marking the completion of a 360-degree transformation from a direct-to-consumer homeowners insurance MGA to a provider of infrastructure to other MGAs across various lines of business.
Score: Kin $667 million — Hippo $0.
Lemonade: Right model, wrong entry point
Lemonade, to its credit, has stuck to its guns on the direct-to-consumer thesis. Lemonade founder Daniel Schreiber articulated the logic clearly in his 2023 post:
“Insurance is an amazing business, where ‘lifetime value’ (LTV) is often measured in actual lifetime… which is why it can be so lucrative to invest in customer acquisition today, in return for that stream of gross profits in the years and decades to come.”
The problem is not the philosophy — it’s the entry point. Lemonade started in renters insurance, a small market with structurally challenging unit economics: low revenue per customer, high churn and a customer base that hasn’t yet bought a home. The theory was that they would hook customers young and upsell them to homeowners insurance over time.
The graduation model hasn’t worked. In their June 2020 S-1, Lemonade disclosed that they had 12,445 condo/homeowners customers, compared to 732,000 total customers (nearly all renters insurance). That was only 1.7 percent of their renters customers had ever upgraded to a home policy.
According to their 2025 Shareholder Letter, most of Lemonade’s recent growth has come outside of Homeowners multi-peril (which includes renters insurance), which only had a 5.3 percent growth rate to reach $530 million at the end of 2025, compared to Kin’s $667 million.
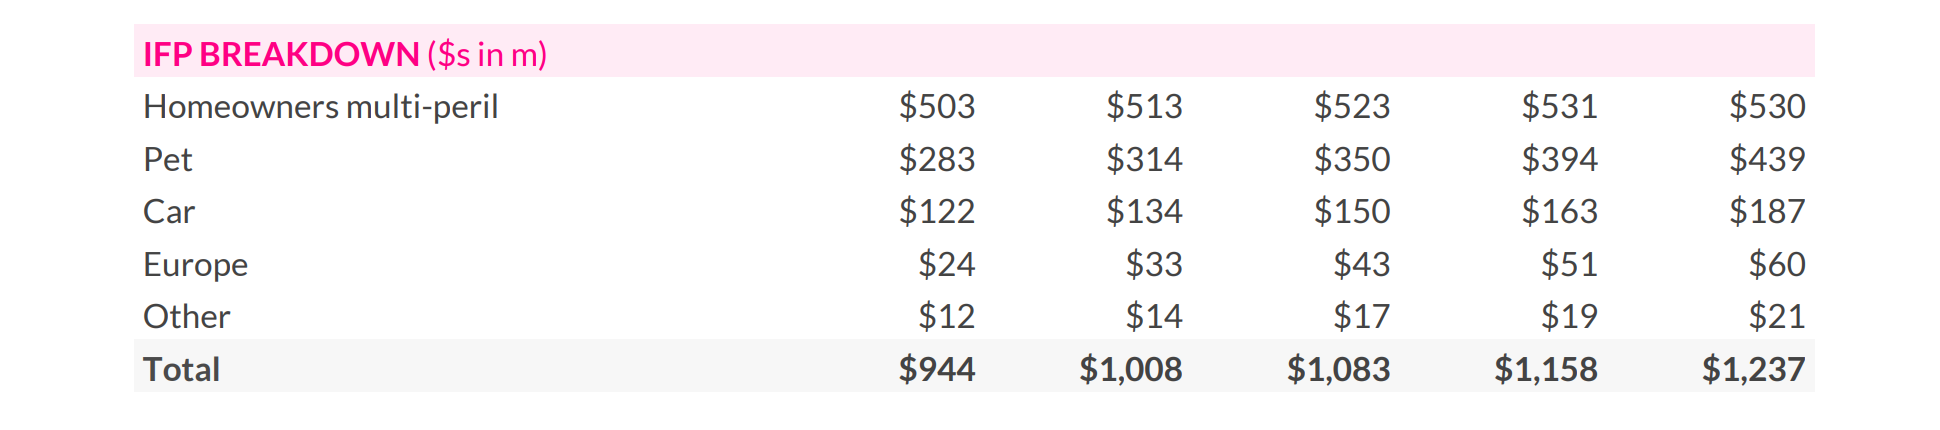
While Lemonade doesn’t disclose the breakdown, we can estimate with simple math. Lemonade discloses average premium in that line of $247/year; most homeowners policies would be in the $1450 range and most renters policies would be in the $175 range. In order to get an average of $247/year, 95% of their policies would be renters!1 If that’s right, Lemonade actually has only ~$26.5 million of true homeowners insurance premium — compared to Kin’s $667 million.
Score: Kin $667 million — Lemonade <$27 million.
Kin: The best version of a big theme
Kin’s Q1 results were released last week and they have done what Hippo abandoned and what Lemonade failed to execute: built a scaled, profitable, genuinely direct-to-consumer homeowners insurance business. With $667 million of premium in force, strong unit economics and no credible DTC competitor in the homeowners category, Kin is not just a winner, it is the category-defining company.
In technology and consumer markets, category leadership does not simply mean a larger company. It means a fundamentally different business with better economics, higher defensibility and a compounding advantage that second-place competitors cannot replicate. The market rewards this with premium multiples — not just proportionally more value, but disproportionately more.
Category winners command disproportionate multiples
Consider the rideshare market. Uber holds ~76 percent U.S. market share vs. Lyft’s ~24 percent. But the valuation gap far exceeds the revenue gap: Uber generates roughly 9x Lyft’s revenue, yet commands more than 30x Lyft’s market capitalization. Lyft is a perfectly viable business; Uber is a category-defining one. The market prices them accordingly.
Or consider food delivery. DoorDash went public in December 2020 at a $72 billion valuation. Grubhub, the original market leader that DoorDash had already displaced, was acquired by Just Eat Takeaway that same year for approximately $7 billion — a tenth of DoorDash’s valuation, despite Grubhub’s longer operating history.
The pattern repeats across categories. The company that wins a large market doesn’t just outperform on revenue, it earns a structural premium. Second-place players, however large in absolute terms, are priced as commodities.
Kin’s position in homeowners insurance is analogous. Hippo has effectively exited the space. Lemonade has fewer than $23 million of real homeowners premium. There is no other well-capitalized DTC homeowners insurer at scale. The DTC homeowners category has one clear winner and it is Kin.
Many investors are scarred by the poor performance of early insurtech IPOs in public markets, but this gets the logic exactly backwards. In every category where a winner emerged, the also-rans ended up looking like poor proxies for the opportunity — which they were.
The relevant question is not “why aren’t Hippo and Lemonade worth more?” The relevant question is: “Do you want to own the company that actually won the DTC homeowners insurance category?” Investors who passed on DoorDash because Grubhub looked cheap made the same analytical error. The losers’ valuations reflect their failure to execute on the thesis — not the size of the prize that the winner gets to claim.
If we assume the average renters policy is $175 and the average homeowners policy is $1,450, then solving 247 = (x × 1,450) + (1-x) × 175 implies that about 95 percent of Lemonade’s premium is renters.
ok but here's what we actually think about d2c right now - it's like knowing your customer and knowing what the fund you're pitching thinks about your customer's category. sounds weird but the vcs writing about d2c in may 2026 are saying something totally different from what they said in january.